As disappointed global stock markets plummeted in response to the U.S. Federal Reserve’s latest stimulus initiative last week, few investors were paying attention to what may have been the Fed’s real intention behind this new plan — mortgage refinancing.
For the longest time, I have been convinced that the housing market holds the key to economic growth (or lack of it) in the United States. As such, I have been hoping against hope that one or more of a long line of presidential candidates would actually have the courage and intellect to recognize and address our main problem.
Instead, I hear how “we need to get America back to work” or “we need to roll back all these regulations that are preventing businesses from investing.” While all of those jingoistic slogans sound good, none of them address the main issue: how to deal with the trillions of dollars in underwater mortgages and the people who hold them.
The Fed, through QE II, (quantitative easing), attempted to push interest rates low enough so that borrowers could stave off foreclosure by refinancing their mortgages. The problem is that lenders insist that the market value of homes to be refinanced must be no lower than 25 percent of the mortgage they carry. That’s a real “Catch-22” for most borrowers, thanks to the decline in housing values over the last three years.
Their houses are now worth a lot less than that. So mortgage holders are in a bind. They can’t sell their property because they won’t get back enough to pay off the loan. They can’t refinance because the house is worth less than the mortgage and they can’t afford the monthly mortgage payments.
As the situation drags on, more and more Americans slip into bankruptcy or walk away from their home/mortgage, leaving an already weakened financial system to pick up the pieces.
Right now, this is just my guess of what the Obama administration may be planning. Over the last week, a number of governmental trial balloons were floated in the media concerning refinancing of up to $1 trillion of mortgage loans on easier terms.
It won’t be a giveaway, if it occurs, in the sense that to qualify for refinancing, you must be current on your mortgage payments and the loans must have been guaranteed by Fannie Mae, Freddie Mac or the Federal Housing Administration. How would it work?
Homeowners who qualify would get a new 30-year loan at, say, 4 percent and pay off 100 percent of the old mortgage (presumably carrying a much higher rate of interest). This is called prepaying your loan in the mortgage business. Your bank receives the proceeds and pays off the old loan to Fannie and Freddie. These two government mortgage entities would receive these billions in prepaid mortgages and dispense them to the ultimate mortgage holders in the mortgage-backed securities market.
Now, guess who holds the lion’s share of mortgage-backed securities in this country? You guessed it, the Fed.
That still leaves Fannie and Freddie with a problem. They need to refinance all these new 30-year, 4 percent mortgages. They are also assuming a lot of risk since lending now, when interest rates are at historical lows, is a dicey business. Who will buy them and how can they protect these new mortgage loans from future losses when interest rates begin to rise? The answer was revealed in last week’s Fed announcement.
The Federal Reserve announced that it intends to drive long-term interest rates lower by purchasing long-term U.S. Treasury bonds. The Fed said it will also juggle its $2.65 trillion securities holdings by using its enormous cash flow to buy more mortgage debt.
In other words, since it will be on the receiving end of all these billions in prepaid mortgage money, it will just turn around and use that cash to buy up billions in these new refinanced mortgages. At the same time, by driving long rates lower through their purchase of long dated treasury bonds, they effectively remove the risk of rates rising anytime in the near future. The Fed becomes both buyer and seller of this entire refinancing operation.
The beauty of this move, in my opinion, is that the White House will be able to launch a new refinancing program/stimulus plan without going through Congress for approval. Nor will it add to the deficit, since all of these transactions will be run through the Federal Reserve.
The Republicans may have gotten wind of this, thus the letter to the Federal Reserve Board just prior to their meeting, warning the Fed members not to do anything further to stimulate the economy.
Well, boys, the Fed just blew you off and you can’t do a thing about it.
Is this all a hair-brained scheme of mine borne of too much work and too little vacation? Time will tell. But if I’m right, I would expect an announcement fairly soon.
I have to hand it to the Obama administration if it is true and they can pull this off. The scope of refinancing they are planning will put $2,000 or more a year into borrower’s pockets, which will amount to a huge stimulus program that bypasses Congress and goes straight to the people. I hope I’m right.
Bill Schmick is registered as an investment advisor representative with Berkshire Money Management. Schmick’s forecasts and opinions are purely his own. None of the information presented here should be construed as an endorsement of BMM or a solicitation to become a client of BMM. Direct inquires to Schmick at 888-232-6072 or email him at Bill@afewdollarsmore.com.
 Models walk the organic runway at HVSFW. Ilan Harel
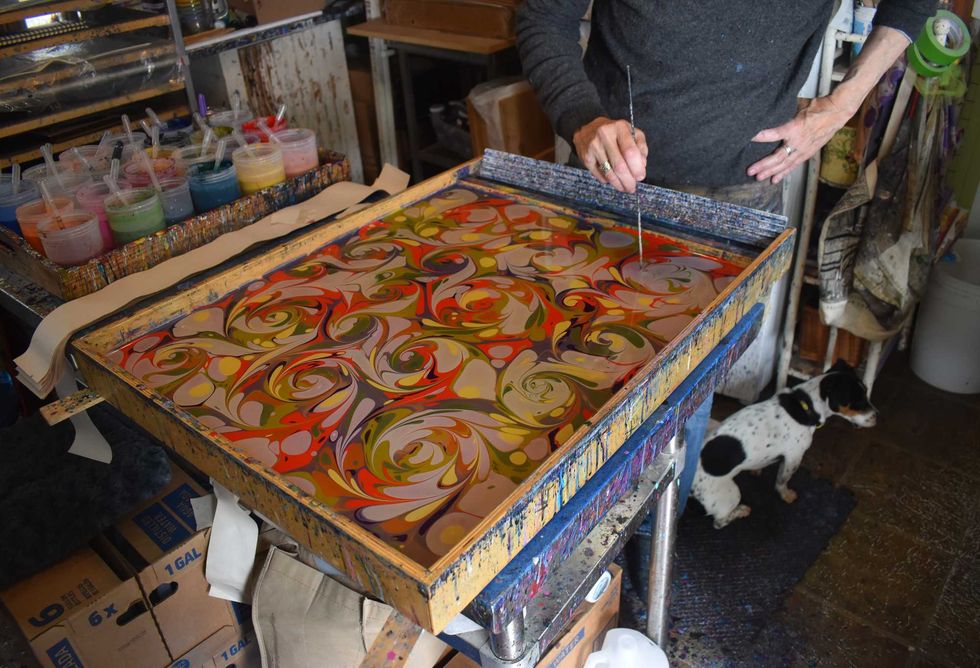 Susan Schneider, owner of Shandell’s, creates a variety of products with marbleized surfaces in her Ashley Falls studio.L. Tomaino
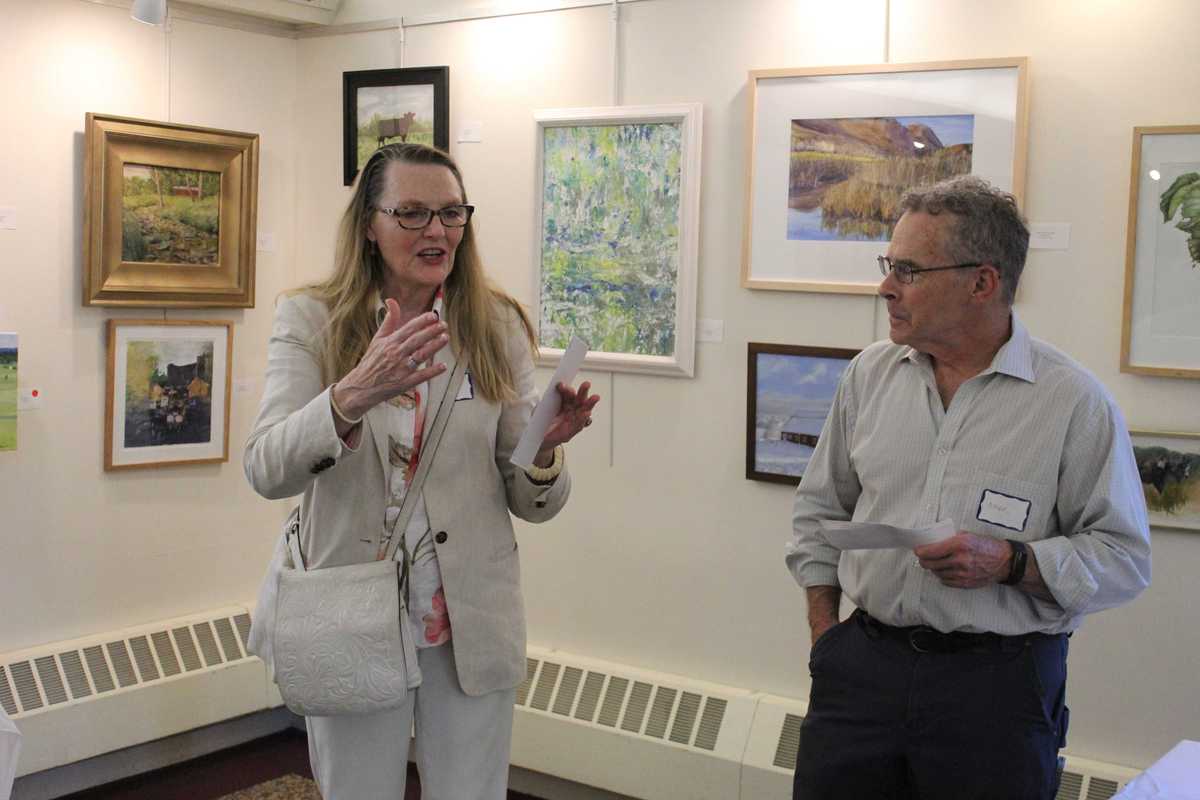
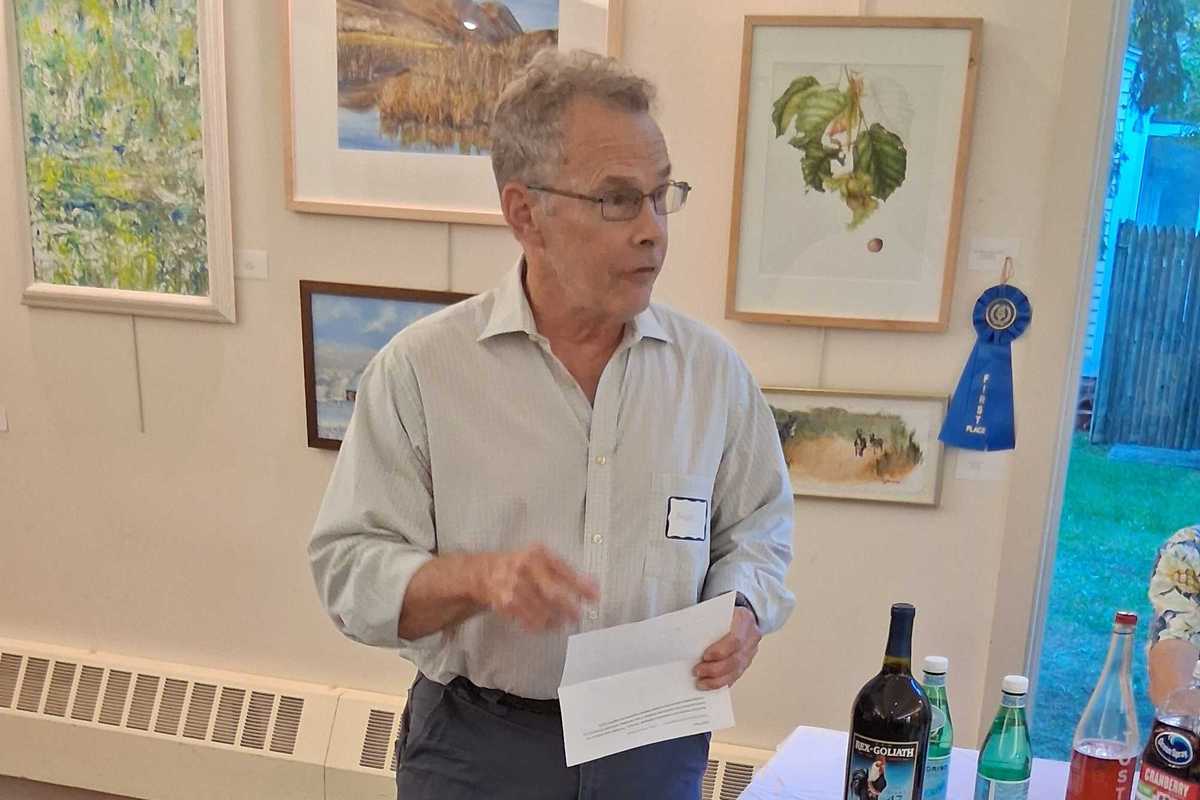 Roger McKee naming the winners with the first place entry over his left shoulder. Patrick L. Sullivan
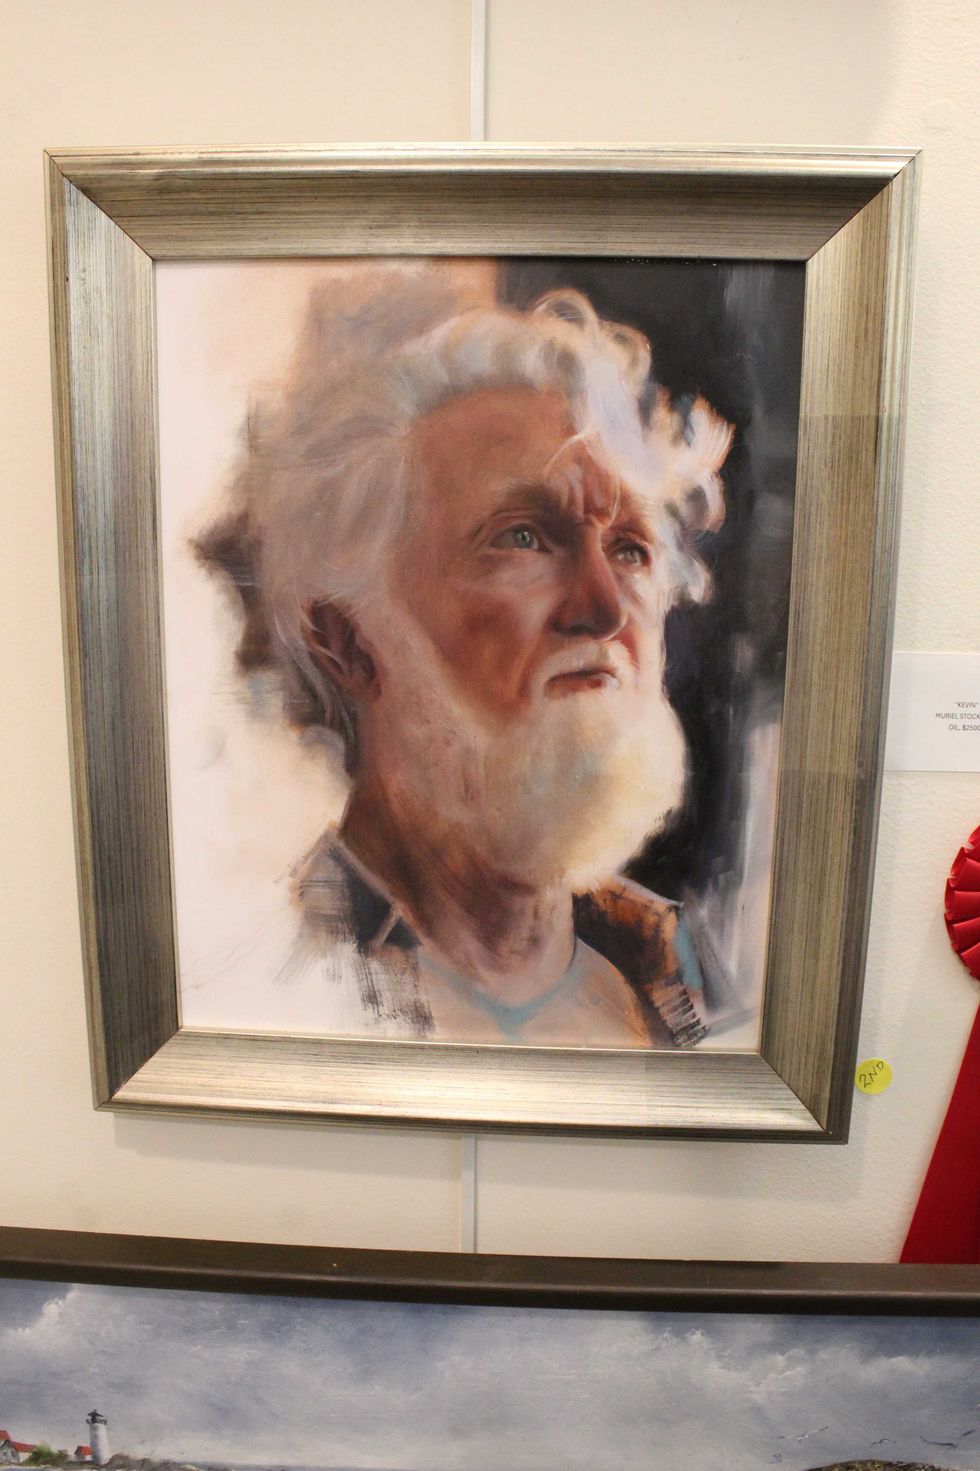 Muriel Stockdale’s “Kevin” took second place in the juried art show at Trinity Episcopal Church.Patrick L. Sullivan