As disappointed global stock markets plummeted in response to the U.S. Federal Reserve’s latest stimulus initiative last week, few investors were paying attention to what may have been the Fed’s real intention behind this new plan — mortgage refinancing.For the longest time, I have been convinced that the housing market holds the key to economic growth (or lack of it) in the United States. As such, I have been hoping against hope that one or more of a long line of presidential candidates would actually have the courage and intellect to recognize and address our main problem.Instead, I hear how “we need to get America back to work” or “we need to roll back all these regulations that are preventing businesses from investing.” While all of those jingoistic slogans sound good, none of them address the main issue: how to deal with the trillions of dollars in underwater mortgages and the people who hold them.The Fed, through QE II, (quantitative easing), attempted to push interest rates low enough so that borrowers could stave off foreclosure by refinancing their mortgages. The problem is that lenders insist that the market value of homes to be refinanced must be no lower than 25 percent of the mortgage they carry. That’s a real “Catch-22” for most borrowers, thanks to the decline in housing values over the last three years. Their houses are now worth a lot less than that. So mortgage holders are in a bind. They can’t sell their property because they won’t get back enough to pay off the loan. They can’t refinance because the house is worth less than the mortgage and they can’t afford the monthly mortgage payments. As the situation drags on, more and more Americans slip into bankruptcy or walk away from their home/mortgage, leaving an already weakened financial system to pick up the pieces.Right now, this is just my guess of what the Obama administration may be planning. Over the last week, a number of governmental trial balloons were floated in the media concerning refinancing of up to $1 trillion of mortgage loans on easier terms. It won’t be a giveaway, if it occurs, in the sense that to qualify for refinancing, you must be current on your mortgage payments and the loans must have been guaranteed by Fannie Mae, Freddie Mac or the Federal Housing Administration. How would it work?Homeowners who qualify would get a new 30-year loan at, say, 4 percent and pay off 100 percent of the old mortgage (presumably carrying a much higher rate of interest). This is called prepaying your loan in the mortgage business. Your bank receives the proceeds and pays off the old loan to Fannie and Freddie. These two government mortgage entities would receive these billions in prepaid mortgages and dispense them to the ultimate mortgage holders in the mortgage-backed securities market.Now, guess who holds the lion’s share of mortgage-backed securities in this country? You guessed it, the Fed.That still leaves Fannie and Freddie with a problem. They need to refinance all these new 30-year, 4 percent mortgages. They are also assuming a lot of risk since lending now, when interest rates are at historical lows, is a dicey business. Who will buy them and how can they protect these new mortgage loans from future losses when interest rates begin to rise? The answer was revealed in last week’s Fed announcement.The Federal Reserve announced that it intends to drive long-term interest rates lower by purchasing long-term U.S. Treasury bonds. The Fed said it will also juggle its $2.65 trillion securities holdings by using its enormous cash flow to buy more mortgage debt. In other words, since it will be on the receiving end of all these billions in prepaid mortgage money, it will just turn around and use that cash to buy up billions in these new refinanced mortgages. At the same time, by driving long rates lower through their purchase of long dated treasury bonds, they effectively remove the risk of rates rising anytime in the near future. The Fed becomes both buyer and seller of this entire refinancing operation.The beauty of this move, in my opinion, is that the White House will be able to launch a new refinancing program/stimulus plan without going through Congress for approval. Nor will it add to the deficit, since all of these transactions will be run through the Federal Reserve. The Republicans may have gotten wind of this, thus the letter to the Federal Reserve Board just prior to their meeting, warning the Fed members not to do anything further to stimulate the economy.Well, boys, the Fed just blew you off and you can’t do a thing about it.Is this all a hair-brained scheme of mine borne of too much work and too little vacation? Time will tell. But if I’m right, I would expect an announcement fairly soon. I have to hand it to the Obama administration if it is true and they can pull this off. The scope of refinancing they are planning will put $2,000 or more a year into borrower’s pockets, which will amount to a huge stimulus program that bypasses Congress and goes straight to the people. I hope I’m right. Bill Schmick is registered as an investment advisor representative with Berkshire Money Management. Schmick’s forecasts and opinions are purely his own. None of the information presented here should be construed as an endorsement of BMM or a solicitation to become a client of BMM. Direct inquires to Schmick at 888-232-6072 or email him at Bill@afewdollarsmore.com.
Latest News
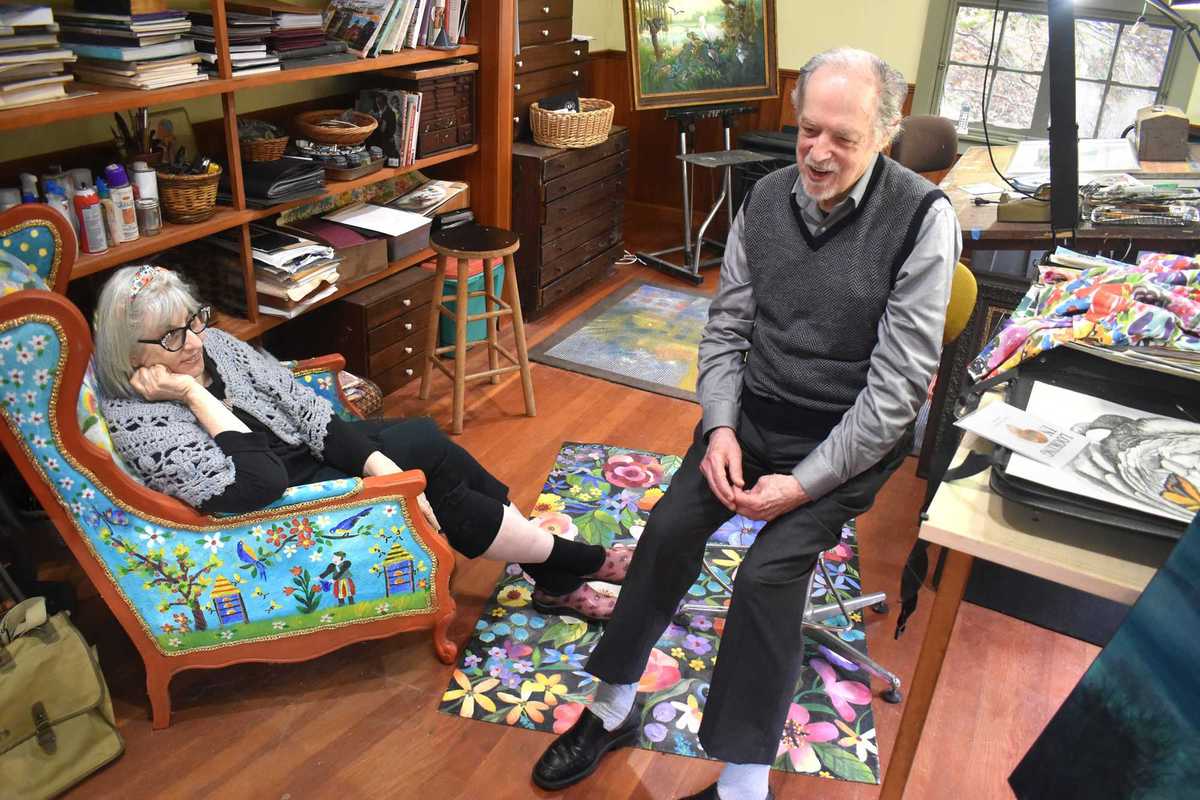
Textile designer Justine Valla sits in her father’s chair, which she painted, alongside her husband, illustrator and muralist Victor Valla, in their Atelier Valla studio.
“I was always drawing as a child,” Justine recalled. Victor dreamed of illustrating magazine covers like those of the “Saturday Evening Post.”
Victor studied design and illustration at Rochester Institute of Technology, then received a fellowship to study painting and printmaking at the University of Illinois at Urbana-Champaigne. He graduated in 1967. The following year, he received a grant from the Tiffany Foundation to study printmaking in Paris at Atelier 17, an experimental graphic arts workshop founded in 1927.
“What a great experience that was!” he recalled.
Returning home after the Paris uprisings of 1968, he discovered that the magazine covers he’d hoped to paint had largely given way to photography. His agent suggested trying record covers, which he pursued along with illustration and graphic design.
He also began teaching at Kean University in New Jersey.
“Kean had a wonderful graphic design and illustration department. I loved teaching Graphic Design, even though I never thought I would.”
He later taught at Syracuse University and Pennsylvania College of Art and Design.
In the late 1980s, he decided to stop teaching and concentrate on his own art. He moved to Falls Village, to a house on the corner of Minor and Prospect Streets.
“I used to call the studio ‘Minor Prospects Atelier,’” he said.
He continued working in illustration and graphic design, creating book covers for stories by H.P. Lovecraft and other authors, along with magazine covers, logos, advertising and murals.
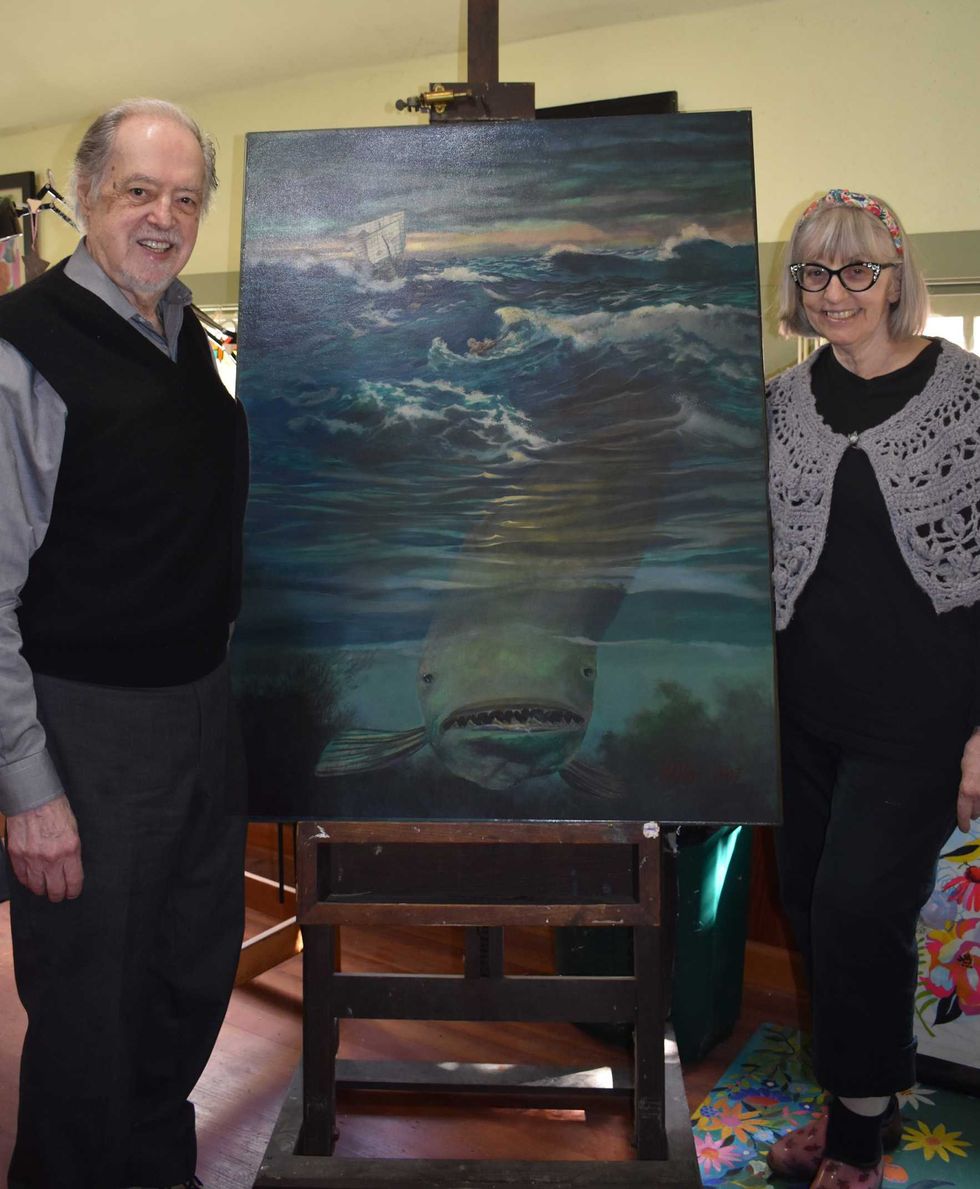 Justine and Victor Valla in their studio with a painting of Victor’s,”Jonah and the Whale.” Robin Roraback
His local commissions include the green and gold Noble Horizons signage and wall murals for the Stockbridge Inn, the Spa at Norwich Inn, Orchards Hotel in Williamstown and the David M. Hunt Library’s children’s section.
Justine grew up in the Bronx and studied at the Fashion Institute of Technology. After graduating, she took on whatever work she could find, including designing toys and novelty items for Russ Berrie. But her true calling was textile design.
She moved to Los Angeles to pursue that calling, where she learned silkscreen printing from 1960s design icon Corita Kent.
“I was in her program at Immaculate Heart College. All fabric design at that time was silk screen. My first job in textile design was in L.A., creating wallpaper for Bob Mitchell Design.”
Justine returned to New York City, where the advent of computers required her to learn new design techniques. She enrolled at Parsons School of Design, studying Photoshop, Illustrator, Lectra U4ia and Kaledo.
Around this time, she met Victor online and moved to Falls Village.
A recruiter found her a job in Arkansas at Dillard’s, a department store chain operating in 30 states and known for its exclusive designer collections.
“They had the best equipment I’d ever seen,” she said.
She became a senior computer-aided design designer there, designing fabric and preparing purchased designs for production.
The Vallas left Falls Village for Little Rock.
“It was a big move,” she said. “It was a different culture, but Little Rock was very progressive.”
The originally planned to stay in Arkansas for five years but ended up remaining for nearly 10.
Then Justine was hit by a car. She suffered injuries to her leg and head and required four years of rehabilitation.
“I lost the ability to paint after the accident. I struggled to paint again.”
The Vallas returned to Connecticut, this time settling in Salisbury, where they’ve lived since 2013.
After leaving Dillard’s, Justine had planned to sell her work through Printsource in New York City, an international showcase for surface and textile design. But after the accident, she no longer had the mobility or energy to travel back and forth to the city.
Instead, she began selling her work locally at craft shows, including clothing, hand-printed tea towels and floorcloths.
She is currently working on selling her collection of textile designs.
In December, Justine will have a show of her tea-themed watercolors at the NorthEast-Millerton Library.
Victor recently exhibited “The American West: A Pictural History” at the NorthEast-Millerton Library. The series, created in the early 1990s, was part of a commission from the Postal Commemorative Society for which he completed 100 paintings in two years.
He hopes to place the series in a museum and has created books from its images, complete with text. Over the years, he has designed many other books that are ready for publication, including “Looking In, Looking Out,” a cosmic view of the universe.
Reflecting on his career, Victor said, “It’s about doing what you love”.
Justine agreed.
To see, purchase or commission work, contact Justine at justinevalla@gmail.com or Victor at victorvalla@comcast.net, or call 860-596-4282.
Want more of our stories on Google? Click here to make us a Preferred Source.
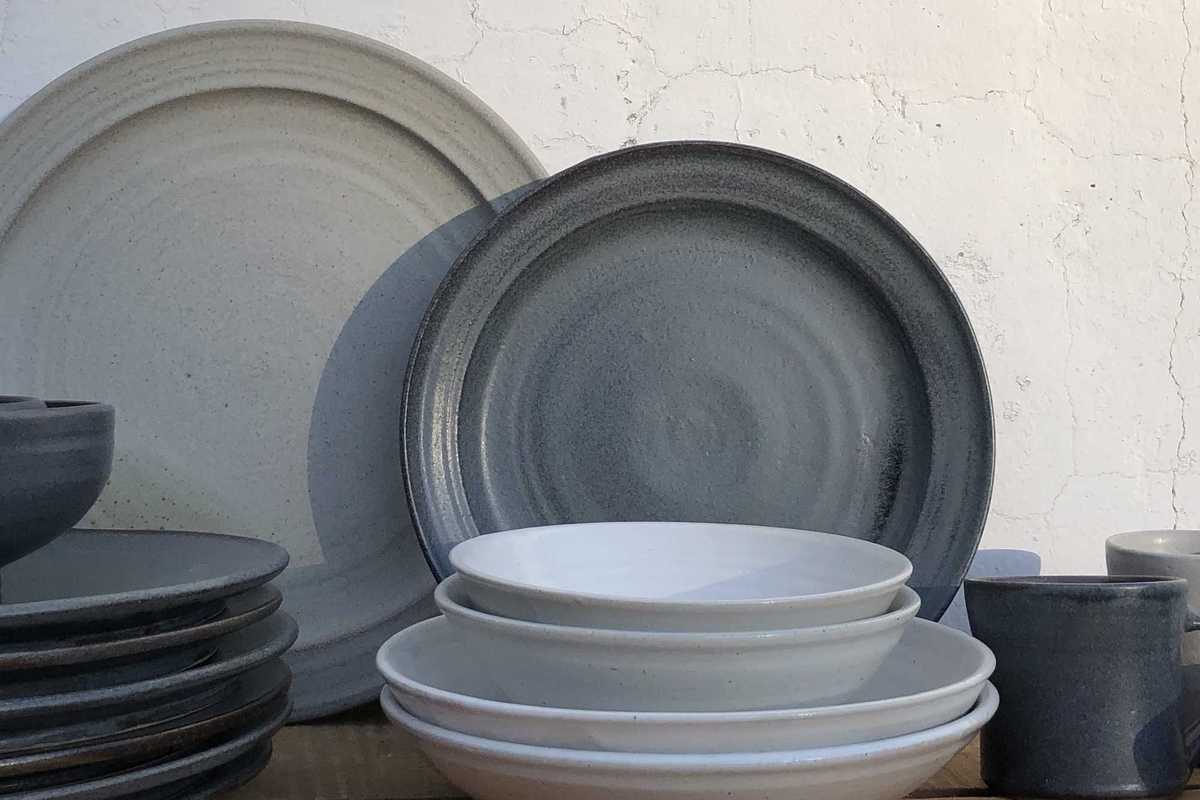
Jane Herold’s beautifully simple dinnerware.
Cornwall ceramicist Jane Herold explained that there’s quite a lot of enthusiasm for Clay Way among the region’s ceramic artists.
“We all need work space, which is hard to find or afford in urban areas. The wood-fire crowd needs lots of wood and outdoor space. This area is great because it’s rural enough for us, but has a wonderfully enthusiastic and supportive population of pottery [patrons].”
While many of the artists are returning from previous years, the loose collection of unofficial organizers likes to keep the event manageable for the public, limiting the number of artists and studios each year. A direct drive from the southernmost point at Ann Heywood’s studio in Wingdale to Herold’s big barn in Cornwall is under 40 minutes. But if you want to catch it all, plan for a full day’s worth of art exploration along some of the most beautiful roads in New England.
Starting at its northernmost point, Herold’s studio will host Matin Malikzada of Afghanistan, whose polished, modern interpretations of traditional forms are instantly recognizable. They’ll be joined by wood-fired ceramicists Steve Johnson, with his raw, organic forms, and Harry Levenstein, whose works relate closely to Johnson’s while making even more direct references to nature.
Herold herself creates work that is both beautiful and utilitarian. Her prolific output of objects is intended to be used by everyday people as part of their daily lives.
Moving south is Todd Piker of Cornwall Bridge Pottery. Piker has been making pots in his giant wood-fired kiln since 1971. The kiln looks more like an ancient blast furnace than something designed to transform clay into ceramics, but over the years, he’s mastered its intricacies and produces an impressive amount of fine work.
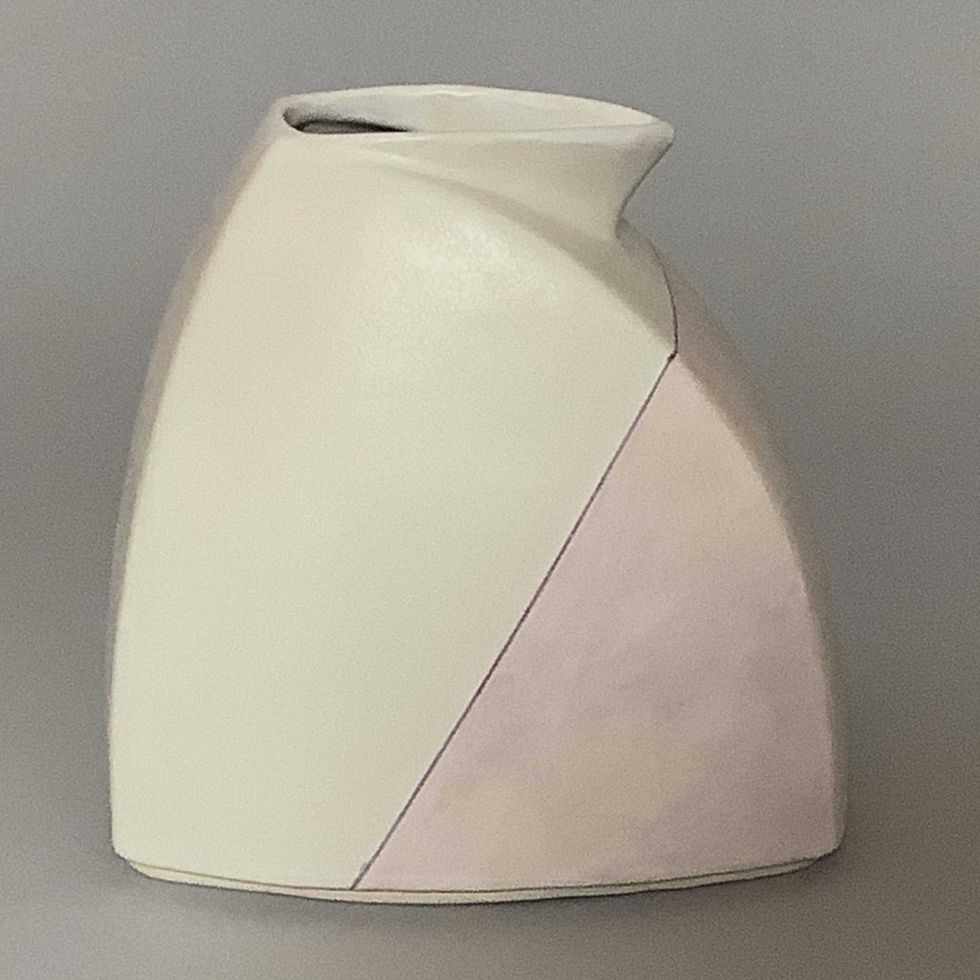 A ceramic vase by Kathleen Heidemann.Provided
Piker will host Sanah Peterson, who works at Cornwall Bridge Pottery and draws inspiration from both her time with Piker and her time traveling the globe as a child. They’ll be joined by Stephanie Haines, whose vibrant, eye-catching work features underglaze illustrations of birds, fruit and the bounty of nature.
Further along in Warren, Jessica Dubin’s pieces will be on display at the studio of Christine Owen. Both artists seem to appreciate the chaos and unpredictable nature of clay but find ways to refine it all using their own unique methods.
Heading east to Washington, Conn., Will Talbot’s creates intricate work while allowing for the unpredictable nature of clay to play a role. His studio will house Tom Knox and his wide variety of textures and forms, as well as New York City-based Alex Lebedev, who lets music and the nature of improvisation guide his work.
There will be two studios participating in South Kent. Alison Palmner, whose page on the Clay Way website states she “strives to achieve a lighthearted meld of human forms, animals and the vessel.” Her studio will host Ben Eberle, who trained under the guidance of legendary potter Toshiko Takaezu; James Guggina, whose intricate work can appear both deliberate and whimsical; and Paula Shalan, who blends rough, unrefined surfaces with polished precision in individual pieces.
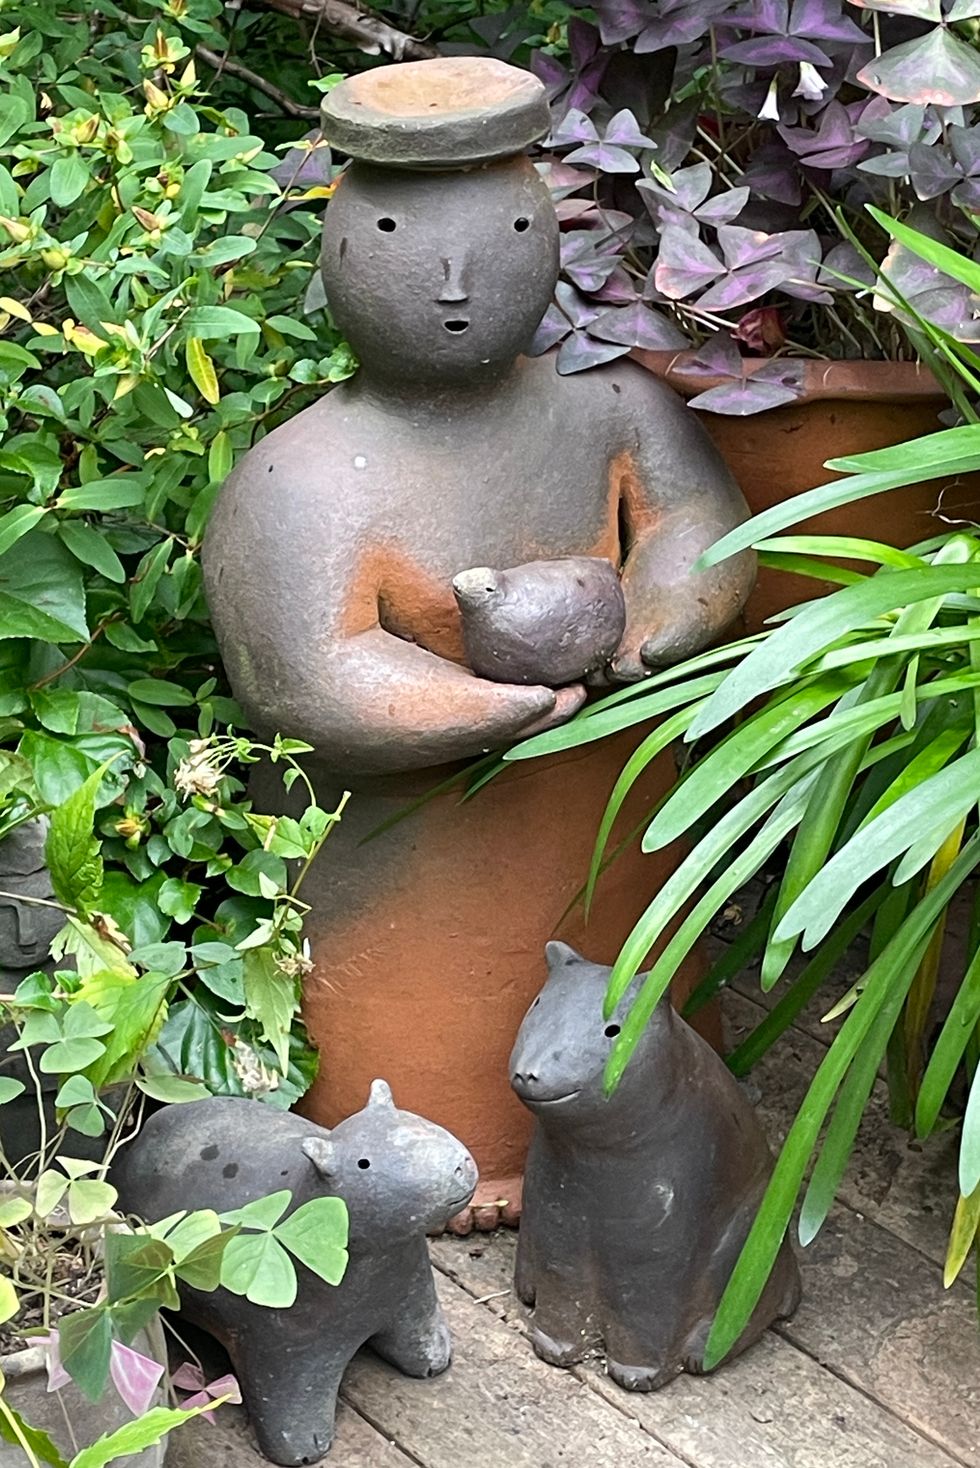 Joy Brown’s delightful ceramic sculptures.Provided
Nearby is Joy Brown, whose work have become a staple of the area, with her figurative sculptures dotting the Northwest Corner. Brown’s studio will also feature Bonnie Levine, who taps into the beauty of chaos and destruction in her work, and Brendan Moore, whose more utilitarian forms are perfect for everyday use.
Finally, the tour crosses the border into Wingdale, New York, where the studios of Drew Montgomery, Ann Heywood and Amy Brenner will host Jackie Sedlock, Lynn Behrendt,and Kathleen Heidemann.
Brenner creates some of the most colorful and vibrant pieces on the tour, while Behrendt’s work is among the most studied and precise. Heywood creates carefully considered, intuitive forms, while Heidemann moves from simple minimalism to intricate textures. Montgomery and Sedlock both find new ways of playing with traditional forms, producing delightfully distinctive pieces.
To learn more about the artists and download a map of participating studios, visit clayway.net
Want more of our stories on Google? Click here to make us a Preferred Source.